Victorine Njong
September 16, 2026
Cost of Residential Assisted Living: 2026 Pricing Guide
Table of Contents
- What the Monthly Base Rate Actually Covers
- Factors Affecting Assisted Living Pricing
- The All-In Cost: Hidden Fees That Surprise Families
- Memory Care vs. Standard Assisted Living Rates
- Assisted Living Payment Options Families Use
- Medicaid Waiver Programs for Assisted Living
- Negotiation Strategies and Tax Deductibility
- Frequently Asked Questions
Last Updated: September 11, 2026
What the Monthly Base Rate Actually Covers
The cost of residential assisted living starts with a monthly base rate that typically bundles rent, utilities, meals, housekeeping, and 24/7 supervision. What it rarely covers are the add-ons that quietly inflate the final bill.
Residential assisted living is a housing-and-care arrangement in which older adults live in a home-like setting and receive help with daily tasks, meals, and supervision. The base rate usually includes:
- Housing, utilities, and maintenance
- Three meals a day plus snacks
- Housekeeping and laundry
- Staff on site around the clock
- Basic help with daily activities
The gap between “base rate” and “actual bill” is where budgeting gets hard: personal care assistance and medication management are often billed separately once a level of care assessment is complete.
Key Takeaway
Ask every community for a written list of what the base rate excludes. The exclusions matter more than the inclusions when you’re building a budget.
Ask every community for a written list of what the base rate excludes. The exclusions matter more than the inclusions when you’re building a budget.
Factors Affecting Assisted Living Pricing
Pricing reflects how much hands-on help a resident needs, not just the room they occupy. Two people in identical apartments can pay very different amounts.
How Level of Care Assessments Change Your Bill
A level of care assessment measures how independently a resident manages activities of daily living (ADLs) such as bathing, dressing, eating, and moving around. The more assistance required, the higher the monthly rate.
Assessments are usually repeated over time, and a decline in mobility or memory can move a resident into a higher care tier and a higher bill. Ask how often reassessments happen and whether rates change mid-lease.
Geographic Cost Variance and Facility Size
Location drives cost as much as care does. Urban markets and higher cost-of-living areas run higher than rural ones, and geographic cost variance can be substantial even within one metro area.
Facility size plays a role too: large corporate communities spread overhead across many residents, while smaller residential homes may price by staffing ratios rather than square footage.
| Factor | What It Changes | What to Ask |
|---|---|---|
| Level of care | Monthly rate tier | How often is care reassessed? |
| Location | Base pricing | What do nearby communities charge? |
| Facility size | Staffing and overhead | What is the staff-to-resident ratio? |
| Amenities | Optional add-ons | Which amenities cost extra? |
The All-In Cost: Hidden Fees That Surprise Families
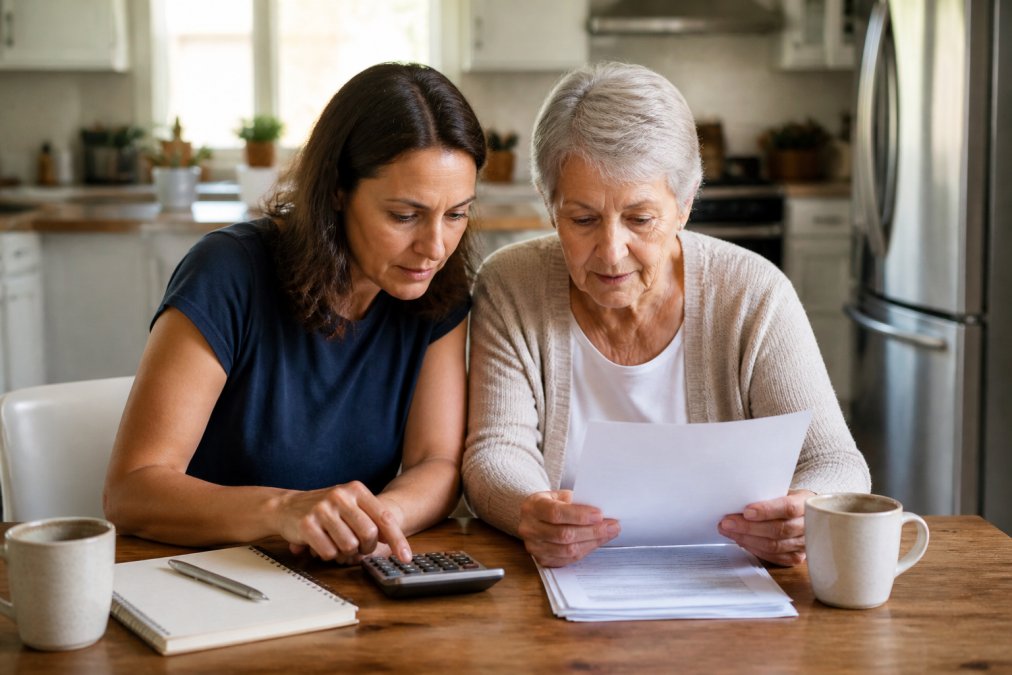
The all-in cost is the number that actually matters, and it is almost never the number quoted first. Hidden fees are the most common source of budget shock, and the reason is structural: base rates are priced to be advertised, while add-ons are priced to be billed.
Why the Base Rate and the Bill Diverge
A published base rate typically reflects the lowest care tier and an occupancy assumption. Once a resident moves in, three things push the bill up:
- A level-of-care reassessment moves the resident into a higher tier, which raises the recurring monthly charge.
- À la carte services, medication management, incontinence care, escorts to meals, reminders, get added line by line.
- One-time and periodic fees, community fees, annual increases, and seasonal charges, land on top of the recurring total.
A family budgeting from the quoted base rate can be off by a meaningful margin within the first 60 to 90 days, the gap is largest for residents who enter at a higher acuity level or decline faster than predicted.
The Line Items That Inflate the Bill
Watch for these, and ask for each in writing:
- Community fee or move-in fee: a one-time charge, often equal to roughly one month’s rent, and frequently non-refundable.
- Care level surcharges: tiered monthly add-ons triggered by the assessment.
- Medication management: often billed per medication pass or as a flat monthly fee that scales with the number of prescriptions.
- Incontinence and personal care supplies: sometimes included, sometimes billed back.
- Transportation: medical appointments may carry a per-trip or per-mile fee; scheduled group outings are usually free.
- Respite care: short-term stays are typically priced at a higher daily rate than the amortized monthly rate.
- Supplemental services: salon, podiatry, physical therapy, specialty meals, guest meals.
- Annual rate increase: most communities raise rates yearly; ask for the historical percentage, not a promise.
Watch Out
A community fee is often non-refundable even if your parent moves out within weeks. Confirm the refund policy in writing before you sign anything, and ask specifically whether the fee is prorated if the resident passes away or transfers to a higher level of care on site.
A community fee is often non-refundable even if your parent moves out within weeks. Confirm the refund policy in writing before you sign anything, and ask specifically whether the fee is prorated if the resident passes away or transfers to a higher level of care on site.
Build a True-Cost Worksheet Before You Tour
A single-page worksheet turns a sales conversation into a comparison. For each community, capture:
| Line item | Base rate quote | Realistic all-in estimate |
|---|---|---|
| Monthly base rate | ||
| Level-of-care tier (current) | ||
| Level-of-care tier (12-month projection) | ||
| Medication management | ||
| Personal care add-ons | ||
| Transportation | ||
| Annual increase (historical %) | ||
| One-time community fee (amortized over 24 months) |
Add the rows, then divide the one-time fee across a realistic length of stay. Compare the bottom number, not the base rate.
Key Takeaway
Ask every community for a written list of what the base rate excludes, plus the last three years of rate increases. The exclusions and the increase history matter more than the inclusions when you’re building a budget.
Ask every community for a written list of what the base rate excludes, plus the last three years of rate increases. The exclusions and the increase history matter more than the inclusions when you’re building a budget.
Questions That Surface the Real Number
- “If my mother’s care level goes up in month four, what does the bill look like?”
- “Which of these services are included at every tier, and which are always à la carte?”
- “What was your average annual rate increase over the last three years?”
- “Is the community fee refundable, prorated, or forfeited?”
- “Are there charges that only appear on the year-end statement?”
Families who ask these five questions before signing report fewer billing surprises than those who compare only base rates.
Memory Care vs. Standard Assisted Living Rates
Memory care costs more than standard assisted living because it requires specialized staffing, secured environments, and more supervision. Families of seniors with dementia should expect a higher monthly figure.
The difference comes down to staffing intensity: memory care units need staff trained to handle wandering, confusion, and behavioral changes, and that coverage costs more to deliver.
Providence Assisted Living Solutions supports memory loss and cognitive changes in a familiar, home-like setting. For families comparing options, the question is less about price alone and more about whether the environment matches the person’s actual needs.
Assisted Living Payment Options Families Use
Most families blend several payment sources. Assisted living payment options fall into a few categories, and understanding them early prevents rushed decisions.
Private Pay, Long-Term Care Insurance, and Veterans Benefits
Private pay means using personal savings, pensions, or the sale of a home. It is the most common route and the most exposed to out-of-pocket expenses over time.
Long-term care insurance can cover part of the cost if the policy includes assisted living benefits. Families should review the policy’s elimination period and daily benefit caps before assuming coverage.
Veterans benefits may help surviving spouses and veterans. The U.S. Department of Veterans Affairs publishes current eligibility rules and amounts, so check the VA benefits for assisted living directly rather than relying on secondhand figures.
Bridge Loans and Home Equity Conversion
A bridge loan covers costs while a home is being sold, which matters when placement is urgent after a hospital stay or fall. Home equity conversion, including reverse mortgages, lets homeowners access equity without selling immediately.
Both carry real costs. Bridge loans often come with higher interest rates, and reverse mortgages have long-term financial implications. Talk to a financial advisor before committing.
Pro Tip
If a hospital discharge is driving the timeline, ask the discharge planner about short-term respite care. It buys you weeks to make a careful decision instead of a panicked one.
If a hospital discharge is driving the timeline, ask the discharge planner about short-term respite care. It buys you weeks to make a careful decision instead of a panicked one.
Medicaid Waiver Programs for Assisted Living
Medicaid waiver programs are state-administered and can help cover assisted living costs for people who meet financial and functional eligibility rules. They are not automatic, and waiting lists are common.
Because these programs are run at the state level, eligibility thresholds, covered services, and application processes vary widely. There is no single national figure for what a waiver covers.
The practical move is to contact your state’s Medicaid office directly and ask which waiver programs cover assisted living in your area. Medicaid home and community-based services explains how these waivers are structured. Apply early, since approval can take months.
Negotiation Strategies and Tax Deductibility
Two angles most cost guides skip: you can sometimes negotiate, and you may be able to deduct. Both require preparation, and both reward families who ask before signing rather than after.
When and How to Negotiate
Assisted living is a priced product with variable occupancy, so there is room to negotiate at the right moment. Leverage is highest when a community has open rooms, when a resident enters at a higher care tier, and when a family can commit to a longer stay or a larger upfront deposit.
Levers that families commonly use:
- Waived or reduced community fee. The one-time move-in fee is the most negotiable line item because it is not tied to recurring care costs.
- Rate lock for a set period. Ask for the base rate to be frozen for 12 or 24 months, or for annual increases to be capped at a stated percentage.
- Trial or respite-to-permanent credit. If you start with respite care, ask whether the respite fees convert to a credit if the resident stays.
- Tiered care pricing. Ask whether the next care tier can be quoted at a blended rate rather than the full step-up.
- Second-person discount. For couples, ask about a shared-room or companion rate.
Timing matters: the last week of a quarter and the winter months, when move-ins slow, are common windows of flexibility. Get every concession in writing as an addendum to the residency agreement, and confirm whether it survives a change in ownership or management.
Pro Tip
If a hospital discharge is driving the timeline, ask the discharge planner about short-term respite care. It buys you weeks to make a careful decision instead of a panicked one, and it gives you a trial run before you negotiate a long-term rate.
If a hospital discharge is driving the timeline, ask the discharge planner about short-term respite care. It buys you weeks to make a careful decision instead of a panicked one, and it gives you a trial run before you negotiate a long-term rate.
Tax Deductibility: What the IRS Actually Allows
Some assisted living costs may be deductible as medical expenses, but the rules are specific. Under IRS rules, qualified long-term care services are medical expenses, and part of a monthly fee can qualify when the primary reason for being there is medical care.
The practical mechanics:
- Medical expense deduction threshold. Medical expenses are deductible only to the extent they exceed a percentage of adjusted gross income, so the deduction is most valuable to families with significant unreimbursed costs.
- Qualified long-term care services. These include necessary diagnostic, preventive, therapeutic, curing, treating, mitigating, and rehabilitative services, plus maintenance and personal care services required by a chronically ill individual under a plan of care.
- Allocation of the monthly fee. When a resident is in assisted living primarily for medical care, a portion of the fee attributable to medical care and personal care services may be deductible; the room-and-board portion generally is not, unless the person is chronically ill and the care is provided under a plan of care.
- Long-term care insurance premiums. Premiums can count as medical expenses, subject to age-based limits.
- Documentation. Keep the residency agreement, the care plan, the level-of-care assessment, and itemized monthly invoices. These are the records a tax preparer will need.
The IRS publishes the governing rules in IRS Publication 502, Medical and Dental Expenses. Because deductibility depends on individual circumstances, health status, and how the community bills, confirm with a tax professional rather than assuming.
A Framework for the Whole Conversation
- Get the all-in monthly figure in writing, not the base rate
- Confirm which fees are refundable and which are forfeited
- Ask how rates change as care needs rise, and request the last three years of increases
- Negotiate the community fee, a rate lock, or a trial credit before signing
- Check Medicaid waiver eligibility in your state
- Review long-term care insurance and veterans benefits
- Ask the community for an itemized invoice sample so you can see how medical vs. room-and-board charges are separated
- Consult a tax professional about deductibility and keep the care plan and assessments on file
Frequently Asked Questions
Does Medicare cover the cost of residential assisted living?
Medicare does not cover room and board or personal care in residential assisted living. It may cover short-term skilled nursing stays, doctor visits, and some therapy services. Most families pay through private pay, long-term care insurance, or Medicaid waiver programs. Check your state’s Medicaid agency for waiver eligibility, since rules and waitlists vary by state and by program.
What are the primary factors that influence assisted living monthly rates?
The biggest drivers are level of care assessment results, room type and size, geographic cost variance, and facility amenities. Memory care typically costs more than standard assisted living because it requires specialized staffing and secure environments. Additional services like medication management, personal care assistance, and respite care can add to the monthly base rate. Ask each community for a written fee schedule before you commit.
What are the most common assisted living payment options?
Most families combine private pay with other sources. Common assisted living payment options include long-term care insurance, veterans benefits, Medicaid waiver programs, bridge loans, and home equity conversion. Some families sell the family home or use a life insurance conversion. A financial planner familiar with elder care can help you match options to your parent’s assets and income.
How do Medicaid waiver programs for assisted living work?
Medicaid waiver programs for assisted living let states use Medicaid funds to cover personal care and support services in a residential setting instead of a nursing home. Eligibility depends on income, assets, and functional need, and most programs have waitlists. Contact your state Medicaid office or Area Agency on Aging to check whether assisted living is covered where your parent lives and what the application process involves.
Recent Post
Big News! Providence Assisted Living Solutions
State Long-Term Care Ombudsman Program
May 12, 2026
Our Friendly Staff
May 27, 2026